https://www.bankchb.com/csr/mashup_eng.jsp?funcId=56d35bcc15
PGh0bWw+IDxoZWFkPjxcL2hlYWQ+IDxib2R5PiAgPGdhcmRlbj4gICA8ZnVuY3M+ICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJhcmVhX2Z1bGxcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU5OTk2XHU5ODAxXCIgZGVzY3JpcHRpb249XCJcdTk5OTZcdTk4MDFcIiBpZD1cImluZGV4XCIgcGFnZT1cImluZGV4XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgPGZ1bmMgbGF5b3V0PVwic3ViYXJlYVwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTg0NjNcdTRFOEJcdTk1NzdcdTc2ODRcdThBNzFcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiMDkyY2MyYzAxNVwiIHBhZ2U9XCIwOTJjYzJjMDE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICA8ZnVuYyBsYXlvdXQ9XCJcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU2QzM4XHU3RThDXHU3NjdDXHU1QzU1XHU5MDRCXHU0RjVDXHU2QTVGXHU1MjM2XCIgZGVzY3JpcHRpb249XCJcdTZDMzhcdTdFOENcdTc2N0NcdTVDNTVcdTkwNEJcdTRGNUNcdTZBNUZcdTUyMzZcIiBpZD1cIjIzNThiNTMyMTVcIiBwYWdlPVwiXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU2QzM4XHU3RThDXHU3NjdDXHU1QzU1XHU3RDQ0XHU3RTU0XHU2N0I2XHU2OUNCXHU1M0NBXHU5MDRCXHU0RjVDXHU2QTVGXHU1MjM2XCIgZGVzY3JpcHRpb249XCJcdTZDMzhcdTdFOENcdTc2N0NcdTVDNTVcdTdENDRcdTdFNTRcdTY3QjZcdTY5Q0JcIiBpZD1cIjBiZjEwM2QwMTVcIiBwYWdlPVwiMGJmMTAzZDAxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU1MjI5XHU1QkIzXHU5NURDXHU0RkMyXHU0RUJBXHU1QzA4XHU1MzQwXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjVlNGI3MjA5MTVcIiBwYWdlPVwiNWU0YjcyMDkxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU5MUNEXHU1OTI3XHU0RTNCXHU5ODRDXHU5NDUxXHU1MjI1XHU4MjA3XHU3QkExXHU3NDA2XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cImY1NzljYjI4MTVcIiBwYWdlPVwiZjU3OWNiMjgxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmFyZWFcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU2QzM4XHU3RThDXC9cdTRGMDFcdTY5NkRcdTc5M0VcdTY3MDNcdThDQUNcdTRFRkJcdTU4MzFcdTU0NEFcdTY2RjhcIiBkZXNjcmlwdGlvbj1cIkNTUlx1NTgzMVx1NTQ0QVx1NjZGOFwiIGlkPVwiN2M1MDA5MTExNVwiIHBhZ2U9XCI3YzUwMDkxMTE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cImh0dHBzOlwvXC93d3cuYmFua2NoYi5jb21cL2NzclwvbWFzaHVwLmpzcD9mdW5jSWQ9NjZjNGM1MTExNVwiPjxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NTIyOVx1NUJCM1x1OTVEQ1x1NEZDMlx1NEVCQVx1NTU0Rlx1NTM3N1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIwNTQxZWE1NjE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJodHRwczpcL1wvd3d3LmJhbmtjaGIuY29tXC9mcm9udGVuZFwvc3Rha2Vob2xkZXJRdWVzdGlvbi5qc3BcIj48XC9mdW5jPiAgICAgPFwvZnVuYz4gICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTZDMzhcdTdFOENcdTk3Q0NcdTYwMjdcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiYmJiN2JhNTIxNVwiIHBhZ2U9XCJcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+ICAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NEYwMVx1Njk2RFx1Njk4Mlx1NkNDMVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI5ZTEyYWE1ZDE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTRGMDFcdTY5NkRcdTY5ODJcdTZDQzFcdTgyMDdcdTcxREZcdTkwNEJcdTdFM0VcdTY1NDhcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiM2M3YmM4N2QxNVwiIHBhZ2U9XCIzYzdiYzg3ZDE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU3QTA1XHU1MkQ5XHU2Q0JCXHU3NDA2XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjk4M2EwZjQ1MTVcIiBwYWdlPVwiOTgzYTBmNDUxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NTE2Q1x1NTNGOFx1NkNCQlx1NzQwNlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJlZWU5NDkzYjE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTUxNkNcdTUzRjhcdTZDQkJcdTc0MDZcdTY3QjZcdTY5Q0JcdTgyMDdcdTg0NjNcdTRFOEJcdTY3MDNcdTkwNEJcdTRGNUNcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiMjM1NWQ1MGExNVwiIHBhZ2U9XCIyMzU1ZDUwYTE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU4NDYzXHU0RThCXHU2NzAzXHU3RTNFXHU2NTQ4XHU4MjA3XHU4NUFBXHU5MTZDXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cImE1YzdlYmU3MTVcIiBwYWdlPVwiYTVjN2ViZTcxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdThBQTBcdTRGRTFcdTdEOTNcdTcxREZcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiMjAzYmQ1ZWIxNVwiIHBhZ2U9XCIyMDNiZDVlYjE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTZDRDVcdTRFRTRcdTkwNzVcdTVGQUFcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiZWY5MDEwMTQxNlwiIHBhZ2U9XCJlZjkwMTAxNDE2XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTZEMTdcdTkzMjJcdTk2MzJcdTUyMzZcdTgyMDdcdTYyNTNcdTY0Q0FcdThDQzdcdTYwNTBcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiYTNiYWIzZTMxNlwiIHBhZ2U9XCJhM2JhYjNlMzE2XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTk4QThcdTk2QUFcdTdCQTFcdTc0MDZcdTgyMDdcdTdBM0RcdTY4MzhcdTUyMzZcdTVFQTZcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiYzBjNDU2MGExNVwiIHBhZ2U9XCJjMGM0NTYwYTE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1OThBOFx1OTZBQVx1N0JBMVx1NzQwNlx1ODIwN1x1N0EzRFx1NjgzOFx1NTIzNlx1NUVBNlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJlYjMwNzExNTE2XCIgcGFnZT1cImViMzA3MTE1MTZcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTY1QjBcdTgyMDhcdTk4QThcdTk2QUFcdTdCQTFcdTc0MDZcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiYWE0ZDNiNDMxNlwiIHBhZ2U9XCJhYTRkM2I0MzE2XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU2NjdBXHU2MTY3XHU4Q0ExXHU3NTIyXHU2QjBBXHU3QkExXHU3NDA2XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjRmODQ1OGIzMTZcIiBwYWdlPVwiNGY4NDU4YjMxNlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1OENDN1x1OEEwQVx1NUI4OVx1NTE2OFx1MzAwMVx1NTAwQlx1OENDN1x1OTYzMlx1OEI3N1x1ODIwN1x1NzFERlx1Njk2RFx1NzlEOFx1NUJDNlx1NEZERFx1OEI3N1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI1ZmE3MmFjZTE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdThDQzdcdThBMEFcdTVCODlcdTUxNjhcdTZBNUZcdTUyMzZcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiNGRhMDEzZWExNVwiIHBhZ2U9XCI0ZGEwMTNlYTE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU1MDBCXHU0RUJBXHU4Q0M3XHU2NTk5XHU0RkREXHU4Qjc3XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjMyNmQxNmM4MTVcIiBwYWdlPVwiMzI2ZDE2YzgxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NzFERlx1Njk2RFx1NzlEOFx1NUJDNlx1NEZERFx1OEI3N1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJhNTRkNDAwMTE1XCIgcGFnZT1cImE1NGQ0MDAxMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8XC9mdW5jPiAgICAgPFwvZnVuYz4gICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTZDMzhcdTdFOENcdTkxRDFcdTg3OEQgXHU2QzM4XHU3RThDXHU3NEIwXHU1ODgzXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cImY4NTA4MjM4MTVcIiBwYWdlPVwiXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU1MTZDXHU1RTczXHU1Rjg1XHU1QkEyXHU4MjA3XHU5NjMyXHU4QTUwXHU1Qjg5XHU1MTY4XHU3REIyXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjgwOTkzZDMzMTVcIiBwYWdlPVwiODA5OTNkMzMxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU2NTc4XHU0RjREXHU1Mjc1XHU2NUIwXHU2NzBEXHU1MkQ5XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjQxZTFiZTFkMTVcIiBwYWdlPVwiNDFlMWJlMWQxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU2NjZFXHU2MEUwXHU5MUQxXHU4NzhEXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cImFmZmUyMDQ0MTZcIiBwYWdlPVwiYWZmZTIwNDQxNlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU4Q0FDXHU0RUZCXHU5MUQxXHU4NzhEXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjEyNzRhNjdmMTVcIiBwYWdlPVwiMTI3NGE2N2YxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTdEQTBcdTgyNzJcdThGNDlcdTU3OEJcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiZDMxMTFmNjQxNVwiIHBhZ2U9XCJkMzExMWY2NDE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU4Q0FDXHU0RUZCXHU2Mjk1XHU4Q0M3XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjg0NjMxOWZkMTVcIiBwYWdlPVwiODQ2MzE5ZmQxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NzZFMVx1ODA3N1x1NjM4OFx1NEZFMVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIxOTg0YWQ3YTE1XCIgcGFnZT1cIjE5ODRhZDdhMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdThENjRcdTkwNTNcdTUzOUZcdTUyNDdcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiOGJjNDQyNTIxNVwiIHBhZ2U9XCI4YmM0NDI1MjE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgPFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NkMyM1x1NTAxOVx1NjZBOFx1ODFFQVx1NzEzNlx1NzZGOFx1OTVEQ1x1NjNFRFx1OTczMlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI5NTZmMGQzZDE1XCIgcGFnZT1cIjk1NmYwZDNkMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NUMwRVx1NTE2NVx1NzRCMFx1NTg4M1x1NkMzOFx1N0U4Q1x1NkExOVx1NkU5NlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI0OGU3YTVmMzE1XCIgcGFnZT1cIjQ4ZTdhNWYzMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NkVBQlx1NUJBNFx1NkMyM1x1OUFENFx1NkUxQlx1OTFDRlx1NTNDQVx1N0JBMVx1NzQwNlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJjYTg3ZmIxMTE1XCIgcGFnZT1cImNhODdmYjExMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1N0RBMFx1ODBGRFx1ODIwN1x1OENDN1x1NkU5MFx1N0JBMVx1NzQwNlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJkMTZjZDlkMTE1XCIgcGFnZT1cImQxNmNkOWQxMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NkMzOFx1N0U4Q1x1NjNBMVx1OENGQ1x1N0JBMVx1NzQwNlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJjMGM3MjU5ZjE1XCIgcGFnZT1cImMwYzcyNTlmMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NEY5Qlx1NjFDOVx1NTU0Nlx1N0JBMVx1NzQwNlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJhN2I5NDMwYzE1XCIgcGFnZT1cImE3Yjk0MzBjMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NkMzOFx1N0U4Q1x1OENDN1x1OEEwQVx1NUMwOFx1NTM0MFwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIzOGE2N2FhZTE1XCIgcGFnZT1cIjM4YTY3YWFlMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgIDxcL2Z1bmM+ICAgICA8ZnVuYyBsYXlvdXQ9XCJcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU1RTc4XHU3OThGXHU4MDc3XHU1ODM0IFx1NzkzRVx1NjcwM1x1NTE3MVx1ODc4RFwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI2OTAzOTQwMTE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NEVCQVx1NkIwQVx1NEZERFx1OTY5Q1x1ODIwN1x1NTkxQVx1NTE0M1x1NUU3M1x1N0I0OVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI4NWQ2ODNhMDE1XCIgcGFnZT1cIjg1ZDY4M2EwMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NEVCQVx1NjI0RFx1NTQzOFx1NUYxNVx1ODIwN1x1NzU1OVx1NEVGQlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIwNjY5ZDNiZTE1XCIgcGFnZT1cIjA2NjlkM2JlMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NTRFMVx1NURFNVx1NTdGOVx1NTI5Qlx1NzY3Q1x1NUM1NVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJhZTE2NDVlYTE1XCIgcGFnZT1cImFlMTY0NWVhMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1ODA3N1x1Njk2RFx1NUI4OVx1NTE2OFx1ODIwN1x1NTA2NVx1NUVCN1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJkM2FhOWJkYzE1XCIgcGFnZT1cImQzYWE5YmRjMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NTE2Q1x1NzZDQVx1N0I1Nlx1NzU2NVx1ODIwN1x1NUY3MVx1OTdGRlx1NTI5QlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJlZThlODI4ZDE1XCIgcGFnZT1cImVlOGU4MjhkMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1OTc1RVx1OENBMVx1NTJEOVx1OTFEMVx1ODc4RFx1NjUyRlx1NjMwMVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI4NjFjMzAzZjE1XCIgcGFnZT1cIjg2MWMzMDNmMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgIDxcL2Z1bmM+ICAgICA8ZnVuYyBsYXlvdXQ9XCJcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU2OUFFXHU4MDAwXHU4MjA3XHU4MEFGXHU1QjlBXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cImVmNzdmYTkyMTVcIiBwYWdlPVwiXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU0RjAxXHU2OTZEXHU2QzM4XHU3RThDXHU3RTNFXHU2NTQ4XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjg0NWI3ZmJjMTVcIiBwYWdlPVwiODQ1YjdmYmMxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU1NzBCXHU5NjlCXHU4QThEXHU4QjQ5XHU2QTE5XHU3QUUwXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjUxMjU0MGNmMTVcIiBwYWdlPVwiNTEyNTQwY2YxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU3ODE0XHU4QTBFXHU1RUE3XHU4QUM3XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjJkYjk0ZWY4MTdcIiBwYWdlPVwiMmRiOTRlZjgxN1wiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgPFwvZnVuYz4gICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTUzQ0JcdTU1ODRcdTkwMjNcdTdENTBcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiYTA1OTRlNWIxNVwiIHBhZ2U9XCJcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTUzQ0JcdTU1ODRcdTkwMjNcdTdENTBcdTVFNzNcdTUzRjBcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiYmMwNWNjM2IxNVwiIHBhZ2U9XCJiYzA1Y2MzYjE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICA8XC9mdW5jPiAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1OTFEMVx1ODc4RFx1NTkyN1x1NTZERVx1OTk0Qlx1NUMwOFx1NTM0MFwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJmMDg0OWM0NDE3XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1OTFEMVx1ODc4RFx1NjU1OVx1ODBCMlx1ODIwN1x1N0QyMFx1OTkwQVx1NjNEMFx1NTM0N1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI0ZDMxNzAxNDE3XCIgcGFnZT1cIjRkMzE3MDE0MTdcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NjUyRlx1NjMwMVx1NTczMFx1NjVCOVx1ODIwN1x1NUYzMVx1NTJFMlx1NzY3Q1x1NUM1NVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJlZTk4NzM2NDE3XCIgcGFnZT1cImVlOTg3MzY0MTdcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1N0RBMFx1ODI3Mlx1OTFEMVx1ODc4RFx1ODIwN1x1NkMzOFx1N0U4Q1x1NzY3Q1x1NUM1NVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIzNWRjZWE3ZjE3XCIgcGFnZT1cIjM1ZGNlYTdmMTdcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1NTU4NFx1NzZFMVx1NzkzRVx1NjcwM1x1OENBQ1x1NEVGQlwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIzNzZlODI2NjE3XCIgcGFnZT1cIjM3NmU4MjY2MTdcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgIDxcL2Z1bmM+ICAgIDxcL2Z1bmM+ICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTUyNkZcdTkwNzhcdTU1QUVcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwidG9wbWVudTFcIiBwYWdlPVwiXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkVOR0xJU0hcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiNTM2ZmJhODYxNVwiIHBhZ2U9XCJcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiaW5kZXhfZW5nLmpzcFwiPjxcL2Z1bmM+ICAgICA8ZnVuYyBsYXlvdXQ9XCJcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiXHU1Qjk4XHU3REIyXHU5OTk2XHU5ODAxXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjRjNGUwYjQ0MTVcIiBwYWdlPVwiXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cImh0dHBzOlwvXC93d3cuYmFua2NoYi5jb21cIj48XC9mdW5jPiAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlx1N0RCMlx1N0FEOVx1NUMwRVx1ODlCRFwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJzaXRlbWFwXCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJzaXRlbWFwLmpzcFwiPjxcL2Z1bmM+ICAgIDxcL2Z1bmM+ICAgIDxmdW5jIGxheW91dD1cInN1YmFyZWFfZnVsbFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJIb21lXCIgZGVzY3JpcHRpb249XCJIb21lXCIgaWQ9XCJpbmRleF9lbmdcIiBwYWdlPVwiaW5kZXhfZW5nXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgPGZ1bmMgbGF5b3V0PVwic3ViYXJlYV9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiTWVzc2FnZSBmcm9tIHRoZSBDaGFpcnBlcnNvblwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIyNmZjOGFiYTE1XCIgcGFnZT1cIjI2ZmM4YWJhMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJNZWNoYW5pc20gb2YgU3VzdGFpbmFibGUgRGV2ZWxvcG1lbnRcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiOGE1ZTU3Y2ExNVwiIHBhZ2U9XCJcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiT3JnYW5pemF0aW9uIGFuZCBNZWNoYW5pc20gb2YgU3VzdGFpbmFibGUgRGV2ZWxvcG1lbnRcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiY2MwY2RiNTMxNVwiIHBhZ2U9XCJjYzBjZGI1MzE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlN0YWtlaG9sZGVyIEVuZ2FnZW1lbnQgYW5kIE1hdGVyaWFsIFRvcGljcyBBbmFseXNpc1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJiODI4ZWI0NjE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiTWF0ZXJpYWwgVG9waWNzIEFuYWx5c2lzXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cImVmZGFiMmIzMTVcIiBwYWdlPVwiZWZkYWIyYjMxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJUaGUgaW1wb3J0YW5jZSBhbmQgaW1wYWN0IG9mIE1hdGVyaWFsIFRvcGljXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjI2MDdlOGU2MTVcIiBwYWdlPVwiMjYwN2U4ZTYxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJTdW1tYXJ5IG9mIFN0YWtlaG9sZGVyIENvbW11bmljYXRpb24gQ2hhbm5lbHMgYW5kIENvbmNlcm5lZCBUb3BpY3NcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiNWQ3YmZjNDIxNVwiIHBhZ2U9XCI1ZDdiZmM0MjE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIk1hbmFnZW1lbnQgYW5kIFRhcmdldCBvZiBNYWpvciBUb3BpY3NcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiM2RkZGRiOWMxNVwiIHBhZ2U9XCIzZGRkZGI5YzE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgPFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiRVNHXC9DU1IgUmVwb3J0c1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJkNzc2MmJjMDE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJodHRwczpcL1wvd3d3LmJhbmtjaGIuY29tXC9jc3JcL21hc2h1cF9lbmcuanNwP2Z1bmNJZD02ZGI4NzI1MjE1XCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiU3Rha2Vob2xkZXIgUXVlc3Rpb25uYWlyZVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJiYmRhNDkwMTE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJodHRwczpcL1wvd3d3LmJhbmtjaGIuY29tXC9mcm9udGVuZFwvc3Rha2Vob2xkZXJRdWVzdGlvbi5qc3A/bGFuZz1lbl91c1wiPjxcL2Z1bmM+ICAgICA8XC9mdW5jPiAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlN1c3RhaW5hYmxlIFJlc2lsaWVuY2VcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiMmUzMzNlNTMxNVwiIHBhZ2U9XCJcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+ICAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkNvbXBhbnkgUHJvZmlsZVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI1NzI4NTE4MzE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiQ29tcGFueSBQcm9maWxlXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjdmYWU4YTNkMTVcIiBwYWdlPVwiN2ZhZThhM2QxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJCdXNpbmVzcyBQZXJmb3JtYW5jZSBhbmQgVGF4IEdvdmVybmFuY2VcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiNDVlZTE4ZDkxNVwiIHBhZ2U9XCI0NWVlMThkOTE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgPFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiQ29ycG9yYXRlIEdvdmVybmFuY2VcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiOGM0MGU4NTcxNVwiIHBhZ2U9XCJcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkNvcnBvcmF0ZSBHb3Zlcm5hbmNlIEZyYW13b3JrICZhbXA7IHRoZSBCb2FyZCBvZiBEaXJlY3RvcnNcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiNGE2MmNkNmIxNVwiIHBhZ2U9XCI0YTYyY2Q2YjE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlBlcmZvcm1hbmNlICZhbXA7IFJlbXVuZXJhdGlvbiBvZiBCb2FyZCBvZiBEaXJlY3RvcnNcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiMjhiNzk0YWQxNVwiIHBhZ2U9XCIyOGI3OTRhZDE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlBhcnRpY2lwYXRpbmcgaW4gVHJhZGUgQXNzb2NpYXRpb25zIGFuZCBMb2JieWluZ1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI2ZjkzNjM4ZDE1XCIgcGFnZT1cIjZmOTM2MzhkMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkJ1c2luZXNzIEludGVncml0eVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIwOGYwZmY5YzE2XCIgcGFnZT1cIjA4ZjBmZjljMTZcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJDb21wbGlhbmNlXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjkzMDExZGMxMTVcIiBwYWdlPVwiOTMwMTFkYzExNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkFudGktTW9uZXkgTGF1bmRlcmluZyBhbmQgQ291bnRlcmluZyBGaW5hbmNpbmcgb2YgVGVycm9yaXNtXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cImMxODU4NDkwMTVcIiBwYWdlPVwiYzE4NTg0OTAxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlJpc2sgTWFuYWdlbWVudCBhbmQgQXVkaXRcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiYWU5ODZlNGMxNVwiIHBhZ2U9XCJhZTk4NmU0YzE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJSaXNrIE1hbmFnZW1lbnQgYW5kIEF1ZGl0XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjI2YmJkYWQ0MTZcIiBwYWdlPVwiMjZiYmRhZDQxNlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJFbWVyZ2luZyBSaXNrIE1hbmFnZW1lbnRcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiMDZkNjczYzYxNlwiIHBhZ2U9XCIwNmQ2NzNjNjE2XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkludGVsbGVjdHVhbCBQcm9wZXJ0eSBNYW5hZ2VtZW50XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjYwMDMwNzZhMTZcIiBwYWdlPVwiNjAwMzA3NmExNlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkluZm9ybWF0aW9uIFNlY3VyaXR5IGFuZCBEYXRhIFByaXZhY3lcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiNWRiM2NjY2ExNVwiIHBhZ2U9XCJcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkluZm9ybWF0aW9uIFNlY3VyaXR5IE1lY2hhbmlzbVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI5ZmZmNzVlMzE1XCIgcGFnZT1cIjlmZmY3NWUzMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiUGVyc29uYWwgSW5mb3JtYXRpb24gUHJvdGVjdGlvblwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJiMzc5MjRhZDE1XCIgcGFnZT1cImIzNzkyNGFkMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8XC9mdW5jPiAgICAgPFwvZnVuYz4gICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJTdXN0YWluYWJsZSBFbnZpcm9ubWVudCBhbmQgRmluYW5jZVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI4Y2VlYzdlNDE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICA8ZnVuYyBsYXlvdXQ9XCJcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiQ2xpbWF0ZS0gYW5kIE5hdHVyZS1SZWxhdGVkIERpc2Nsb3N1cmVzXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjFjNmJhYjdmMTVcIiBwYWdlPVwiXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJDbGltYXRlLWFuZCBOYXR1cmUtUmVsYXRlZCBEaXNjbG9zdXJlc1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI1NmQzNWJjYzE1XCIgcGFnZT1cIjU2ZDM1YmNjMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJDbGltYXRlIGFuZCBOYXR1cmUgUmlzayBNYW5hZ2VtZW50XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjRlYmM3MTA3MTVcIiBwYWdlPVwiNGViYzcxMDcxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiR3JlZW5ob3VzZSBHYXMgUmVkdWN0aW9uIGFuZCBNYW5hZ2VtZW50XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjNmNjRmMWIyMTVcIiBwYWdlPVwiM2Y2NGYxYjIxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiU3VzdGFpbmFibGUgRW5lcmd5IGFuZCBSZXNvdXJjZSBNYW5hZ2VtZW50XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjZjZTdiNTRlMTVcIiBwYWdlPVwiNmNlN2I1NGUxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlN1c3RhaW5hYmxlIFByb2N1cmVtZW50IE1hbmFnZW1lbnRcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiYzE1YTQ4MjgxNVwiIHBhZ2U9XCJjMTVhNDgyODE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiUmVzcG9uc2libGUgRmluYW5jZVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJiZWI2MTlhZDE1XCIgcGFnZT1cImJlYjYxOWFkMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkN1c3RvbWVyIFJpZ2h0cyBhbmQgSW50ZXJlc3RzXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjQ4MzAyYTRlMTVcIiBwYWdlPVwiNDgzMDJhNGUxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJEaWdpdGFsIElubm92YXRpb24gU2VydmljZXNcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiNmM4MTZhZDMxNlwiIHBhZ2U9XCI2YzgxNmFkMzE2XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkZpbmFuY2lhbCBJbmNsdXNpb25cIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiZDY4ZmFkNjcxNVwiIHBhZ2U9XCJkNjhmYWQ2NzE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkVxdWF0b3IgUHJpbmNpcGxlc1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI5MzgwOTY0NDE1XCIgcGFnZT1cIjkzODA5NjQ0MTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiUmVzcG9uc2libGUgSW52ZXN0bWVudFwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI1NGZmMDhlZTE1XCIgcGFnZT1cIjU0ZmYwOGVlMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiUmVzcG9uc2libGUgRmluYW5jaW5nXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjZlOGRiMTRhMTVcIiBwYWdlPVwiNmU4ZGIxNGExNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJGaW5hbmNpYWwgSW5jbHVzaW9uXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjBkYjYyNGE4MTZcIiBwYWdlPVwiMGRiNjI0YTgxNlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJHcmVlbiBUcmFuc2l0aW9uXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjk4NGZiMDEyMTVcIiBwYWdlPVwiOTg0ZmIwMTIxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxcL2Z1bmM+ICAgICA8XC9mdW5jPiAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkhhcHB5IFdvcmtwbGFjZSBhbmQgU29jaWFsIEluY2x1c2lvblwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJjYzhmODdmZTE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJIdW1hbiBSaWdodHMgUHJvdGVjdGlvblwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI4MDlmNWEzMTE1XCIgcGFnZT1cIjgwOWY1YTMxMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJQcm9tb3RpbmcgRGl2ZXJzaXR5IGFuZCBFcXVhbGl0eVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI0OGRlMjZhMTE1XCIgcGFnZT1cIjQ4ZGUyNmExMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJTZXh1YWwgSGFyYXNzbWVudCBQcmV2ZW50aW9uXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjRhNzJhZjhiMTVcIiBwYWdlPVwiNGE3MmFmOGIxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJUYWxlbnQgQXR0cmFjdGlvbiBhbmQgUmV0ZW50aW9uXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjhlNzIwOWVkMTVcIiBwYWdlPVwiXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJFbXBsb3llZSBDb21wb3NpdGlvbiBhbmQgRGl2ZXJzaXR5XCIgZGVzY3JpcHRpb249XCJcIiBpZD1cImNhMjY0MWYzMTVcIiBwYWdlPVwiY2EyNjQxZjMxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50XCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkVtcGxveWVlIENvbXBlbnNhdGlvbiBhbmQgQmVuZWZpdHNcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiZDE2ZWUwZDcxNVwiIHBhZ2U9XCJkMTZlZTBkNzE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkVtcGxveWVlIENvbW11bmljYXRpb24gQ2hhbm5lbFwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI2MDViZmVkZjE1XCIgcGFnZT1cIjYwNWJmZWRmMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkVtcGxveWVlIEN1bHRpdmF0aW9uIGFuZCBEZXZlbG9wbWVudFwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI0ZTQwMmZiZTE1XCIgcGFnZT1cIjRlNDAyZmJlMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJPY2N1cGF0aW9uYWwgU2FmZXR5IGFuZCBIZWFsdGhcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiOTFhYTFjNDExNVwiIHBhZ2U9XCI5MWFhMWM0MTE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiQ2hhcml0YWJsZSBTdHJhdGVneSBhbmQgSW5mbHVlbmNlXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cImM2MzRhOTMyMTVcIiBwYWdlPVwiYzYzNGE5MzIxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkZpbmFuY2lhbCBMaXRlcmFjeSBFZHVjYXRpb25cIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiZDMzMWFjYjUxNVwiIHBhZ2U9XCJkMzMxYWNiNTE1XCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPjxcL2Z1bmM+ICAgICA8XC9mdW5jPiAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkF3YXJkcyBhbmQgUmVjb2duaXRpb25cIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwiYTY3ZjM0NGMxNVwiIHBhZ2U9XCJcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+ICAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudF9lbmdcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiSG9ub3JzLCBSZWNvZ25pdGlvbnMgYW5kIFN1c3RhaW5hYmxlIFBlcmZvcm1hbmNlc1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIxM2FlMTc5NjE1XCIgcGFnZT1cIjEzYWUxNzk2MTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJJbnRlcm5hdGlvbmFsIENlcnRpZmljYXRpb25zXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjYxNmMxZTYxMTVcIiBwYWdlPVwiNjE2YzFlNjExNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICAgPFwvZnVuYz4gICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJGcmllbmRseSBMaW5rc1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIzOGZkOWQ3YzE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgICA8ZnVuYyBsYXlvdXQ9XCJzdWJjb250ZW50X2VuZ1wiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJGcmllbmRseSBMaW5rc1wiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCIyY2IwNDc2NTE1XCIgcGFnZT1cIjJjYjA0NzY1MTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgIDxcL2Z1bmM+ICAgIDxcL2Z1bmM+ICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJTdWIgbWVudVwiIGRlc2NyaXB0aW9uPVwiU3ViIG1lbnVcIiBpZD1cInRvcG1lbnUxX2VuZ1wiIHBhZ2U9XCJcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+ICAgICA8ZnVuYyBsYXlvdXQ9XCJcIiBpc19vcGVuPVwiWVwiIHVsY2xhc3M9XCJcIiBuYW1lPVwiQ0hJTkVTRVwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCJhMWE0MTQyMzE1XCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJpbmRleC5qc3BcIj48XC9mdW5jPiAgICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIlNpdGVtYXBcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwic2l0ZW1hcF9lbmdcIiBwYWdlPVwiXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cInNpdGVtYXBfZW5nLmpzcFwiPjxcL2Z1bmM+ICAgIDxcL2Z1bmM+ICAgIDxmdW5jIGxheW91dD1cIlwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTUxNzZcdTRFRDZcIiBkZXNjcmlwdGlvbj1cIlwiIGlkPVwib3RoZXJcIiBwYWdlPVwiXCIgbGljbGFzcz1cIlwiIGljb25jbGFzcz1cIlwiIHVybD1cIlwiPiAgICAgPGZ1bmMgbGF5b3V0PVwic3ViY29udGVudFwiIGlzX29wZW49XCJZXCIgdWxjbGFzcz1cIlwiIG5hbWU9XCJcdTRFMEJcdThGMDlcdTZDMzhcdTdFOENcL1x1NEYwMVx1Njk2RFx1NzkzRVx1NjcwM1x1OENBQ1x1NEVGQlx1NTgzMVx1NTQ0QVx1NjZGOFwiIGRlc2NyaXB0aW9uPVwiXCIgaWQ9XCI2NmM0YzUxMTE1XCIgcGFnZT1cIjY2YzRjNTExMTVcIiBsaWNsYXNzPVwiXCIgaWNvbmNsYXNzPVwiXCIgdXJsPVwiXCI+PFwvZnVuYz4gICAgPFwvZnVuYz4gICAgPGZ1bmMgbGF5b3V0PVwiXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIk90aGVyXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIm90aGVyX2VuXCIgcGFnZT1cIlwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj4gICAgIDxmdW5jIGxheW91dD1cInN1YmNvbnRlbnRfZW5nXCIgaXNfb3Blbj1cIllcIiB1bGNsYXNzPVwiXCIgbmFtZT1cIkRvd25sb2FkIEVTRyBSZXBvcnRzXCIgZGVzY3JpcHRpb249XCJcIiBpZD1cIjZkYjg3MjUyMTVcIiBwYWdlPVwiNmRiODcyNTIxNVwiIGxpY2xhc3M9XCJcIiBpY29uY2xhc3M9XCJcIiB1cmw9XCJcIj48XC9mdW5jPiAgICA8XC9mdW5jPiAgIDxcL2Z1bmNzPiAgPFwvZ2FyZGVuPiA8XC9ib2R5PjxcL2h0bWw+
Jump to main content


For the best experience, change the screen to portrait mode.
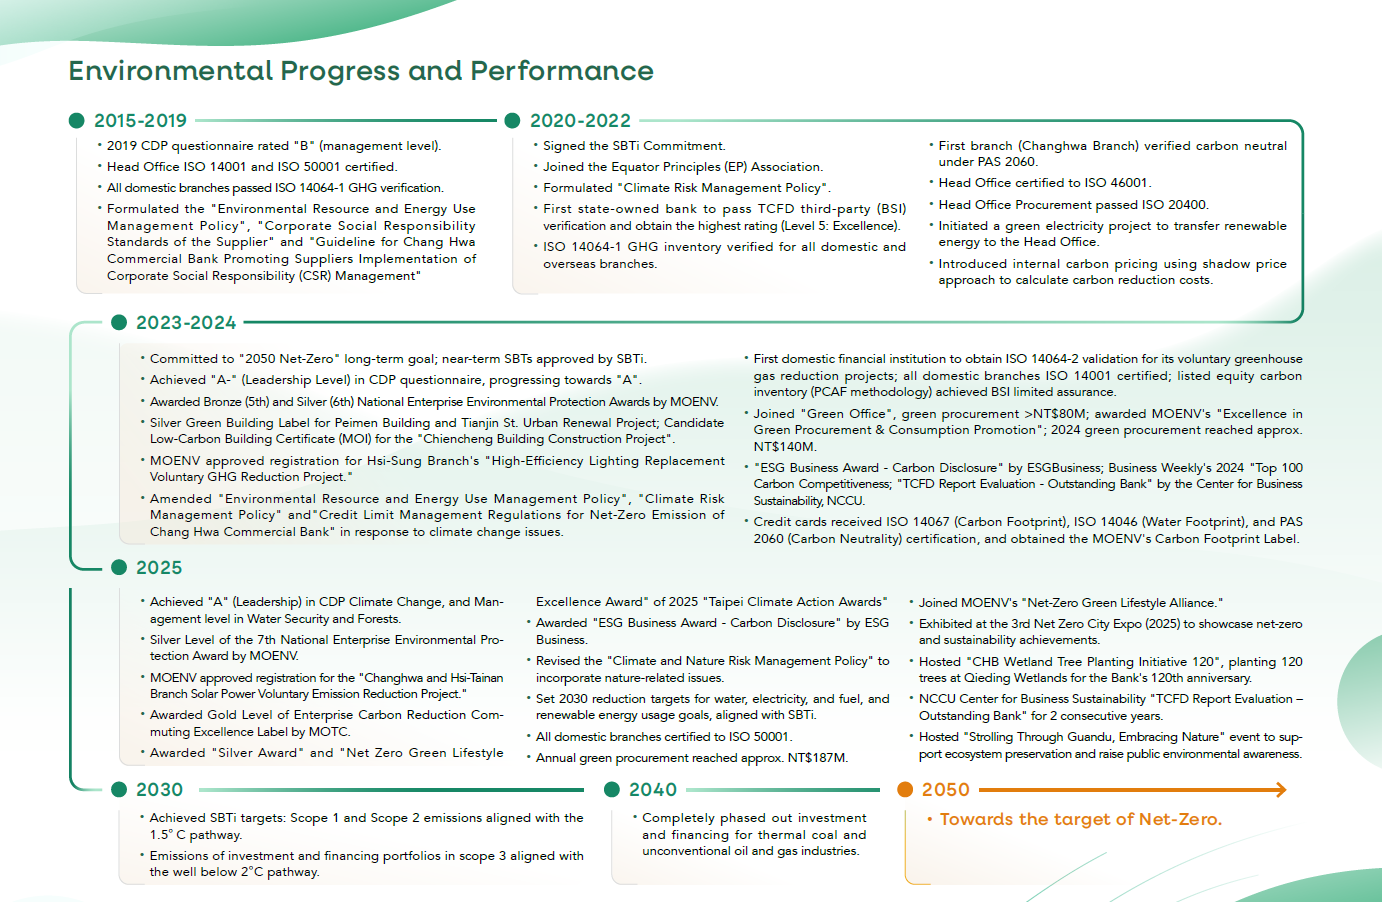
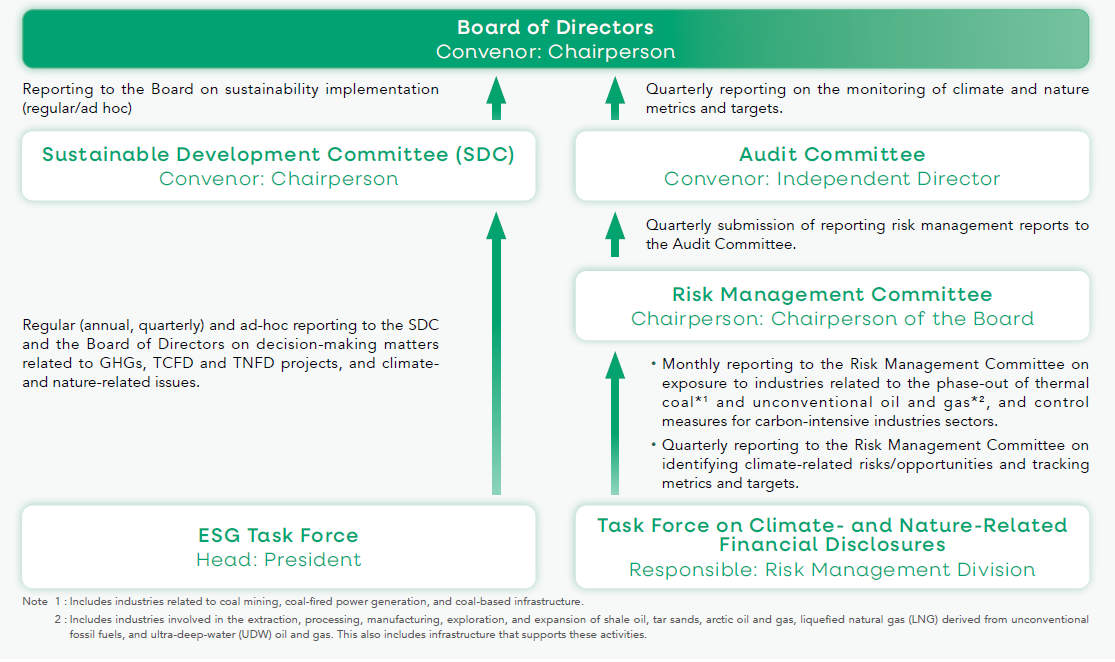
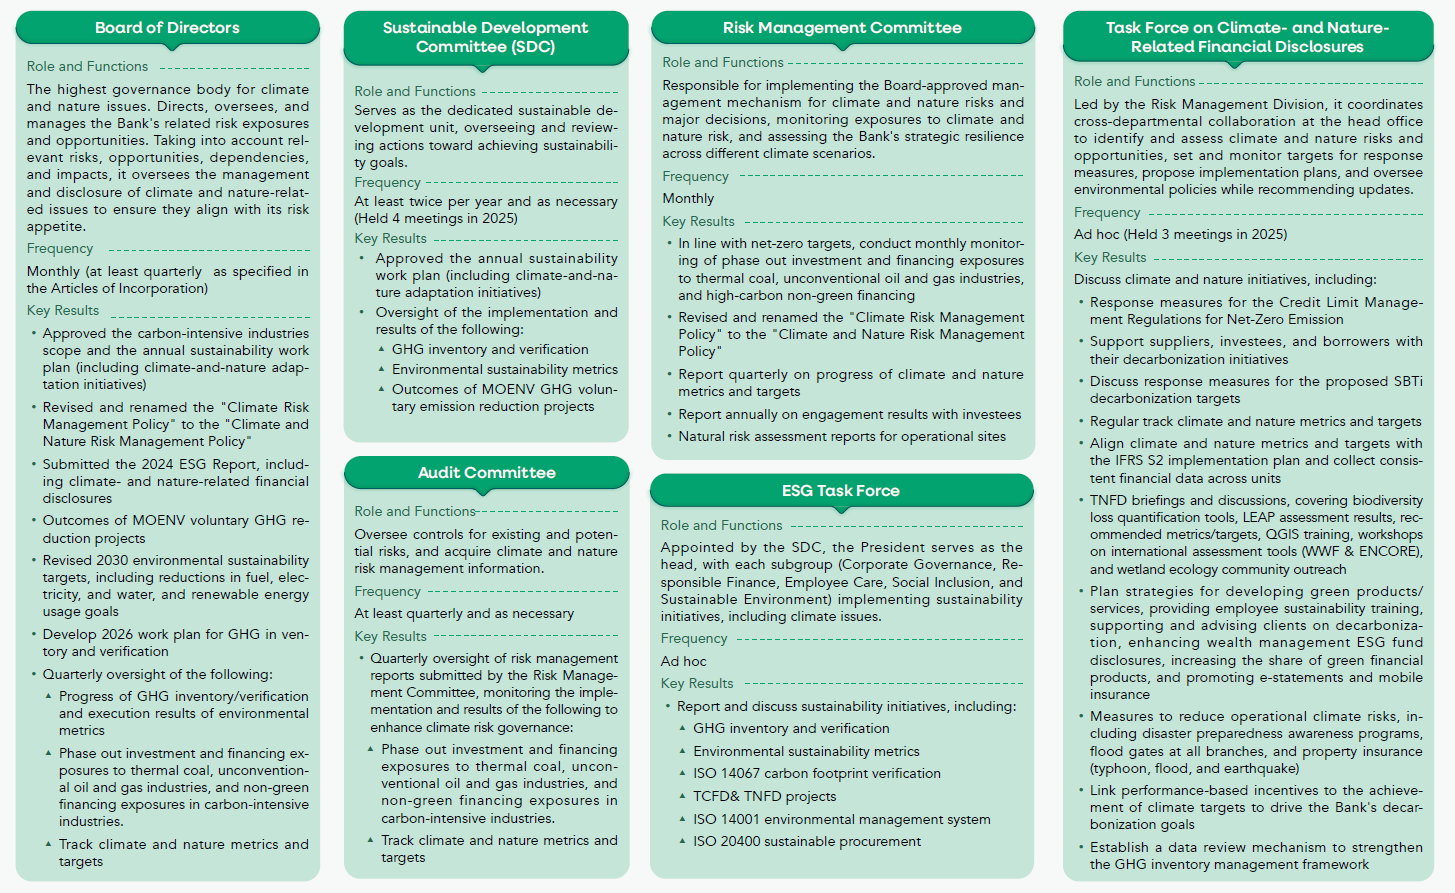
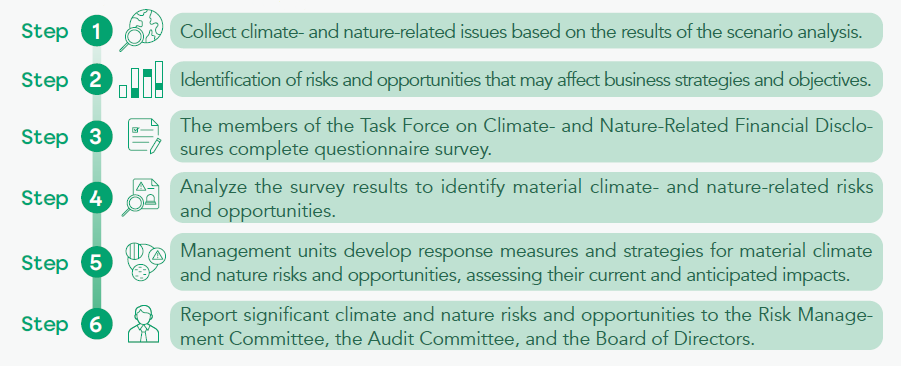
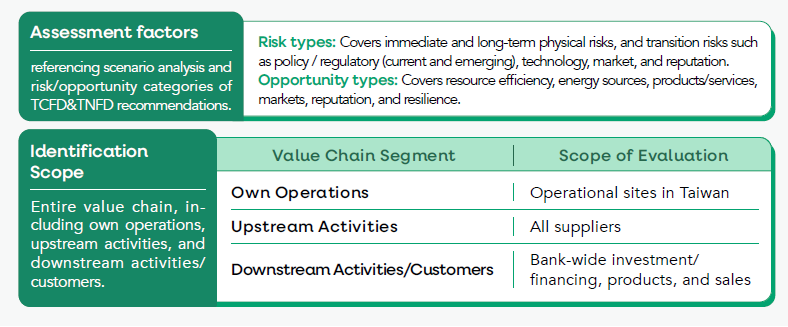
The Bank's climate and nature governance framework for climate- and nature-related issues designates the Board of Directors as the highest governing body. It further outlines the roles and responsibilities of relevant governance structures, including the Sustainable Development Committee, Audit Committee, Risk Management Committee, ESG Task Force, and the Task Force on Climate- and Nature-Related Financial Disclosure (Task Force on TCFD&TNFD). The oversight and implementation processes are outlined as follows:
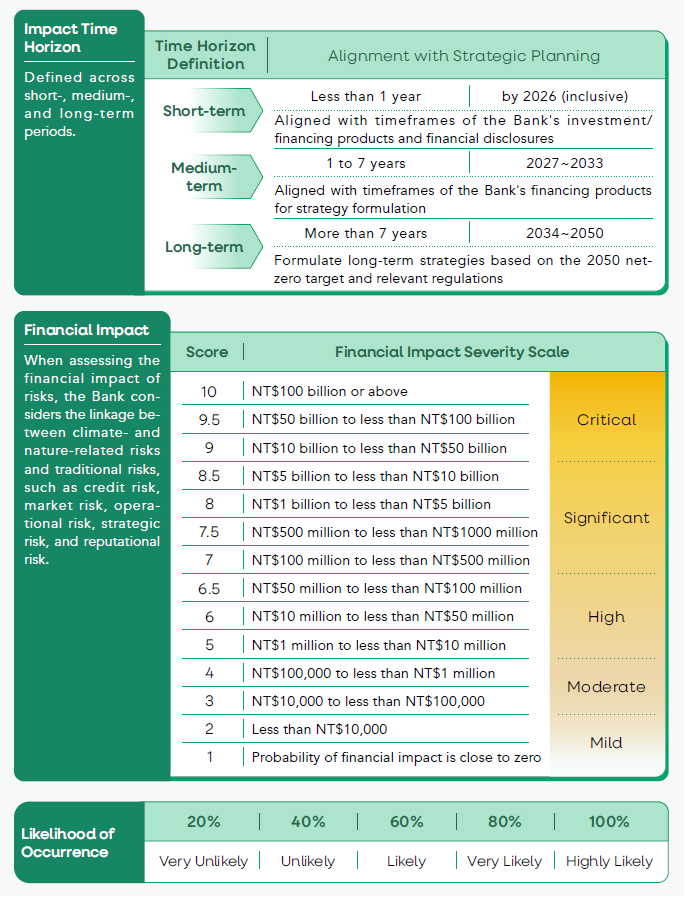
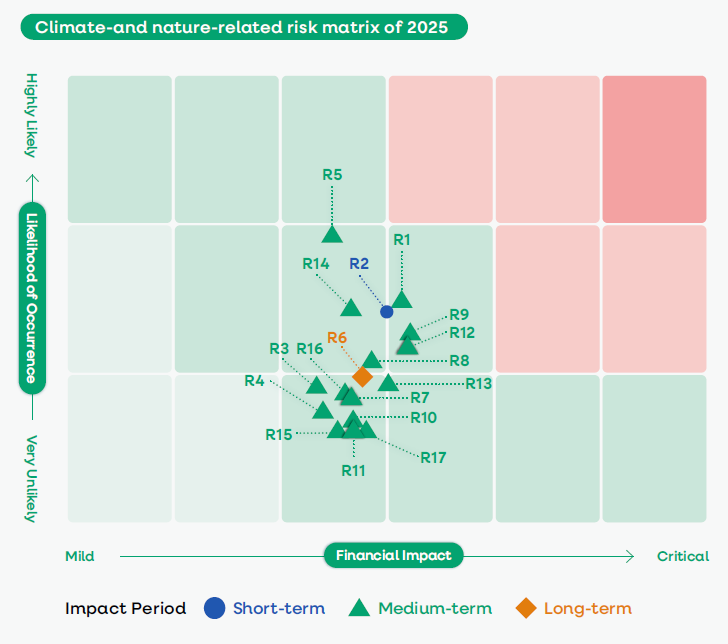
Climate and Nature Risk and Opportunity Affecting the Bank's Outlook
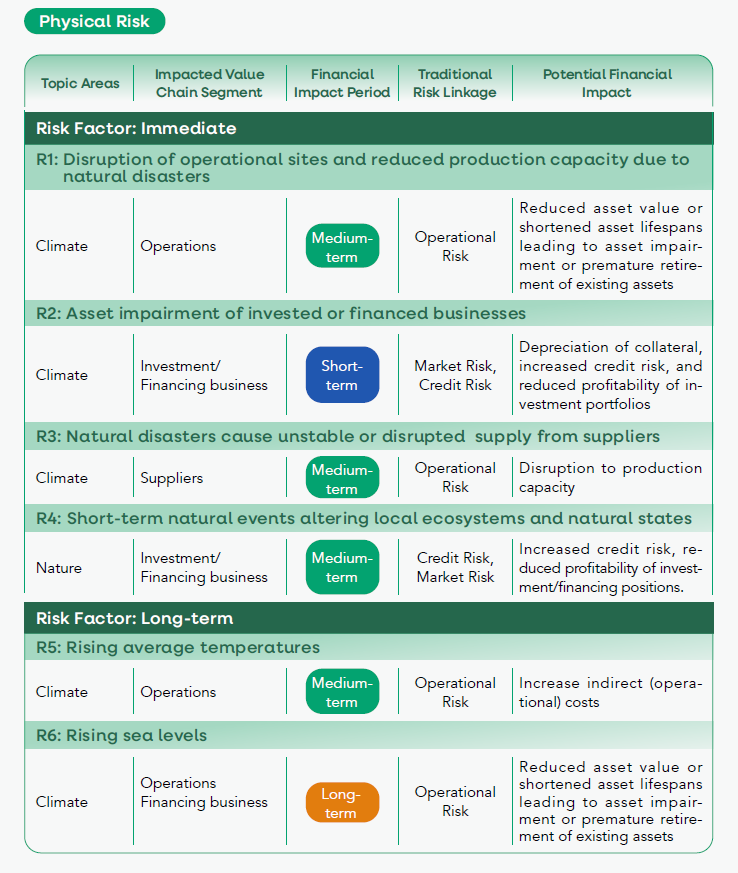
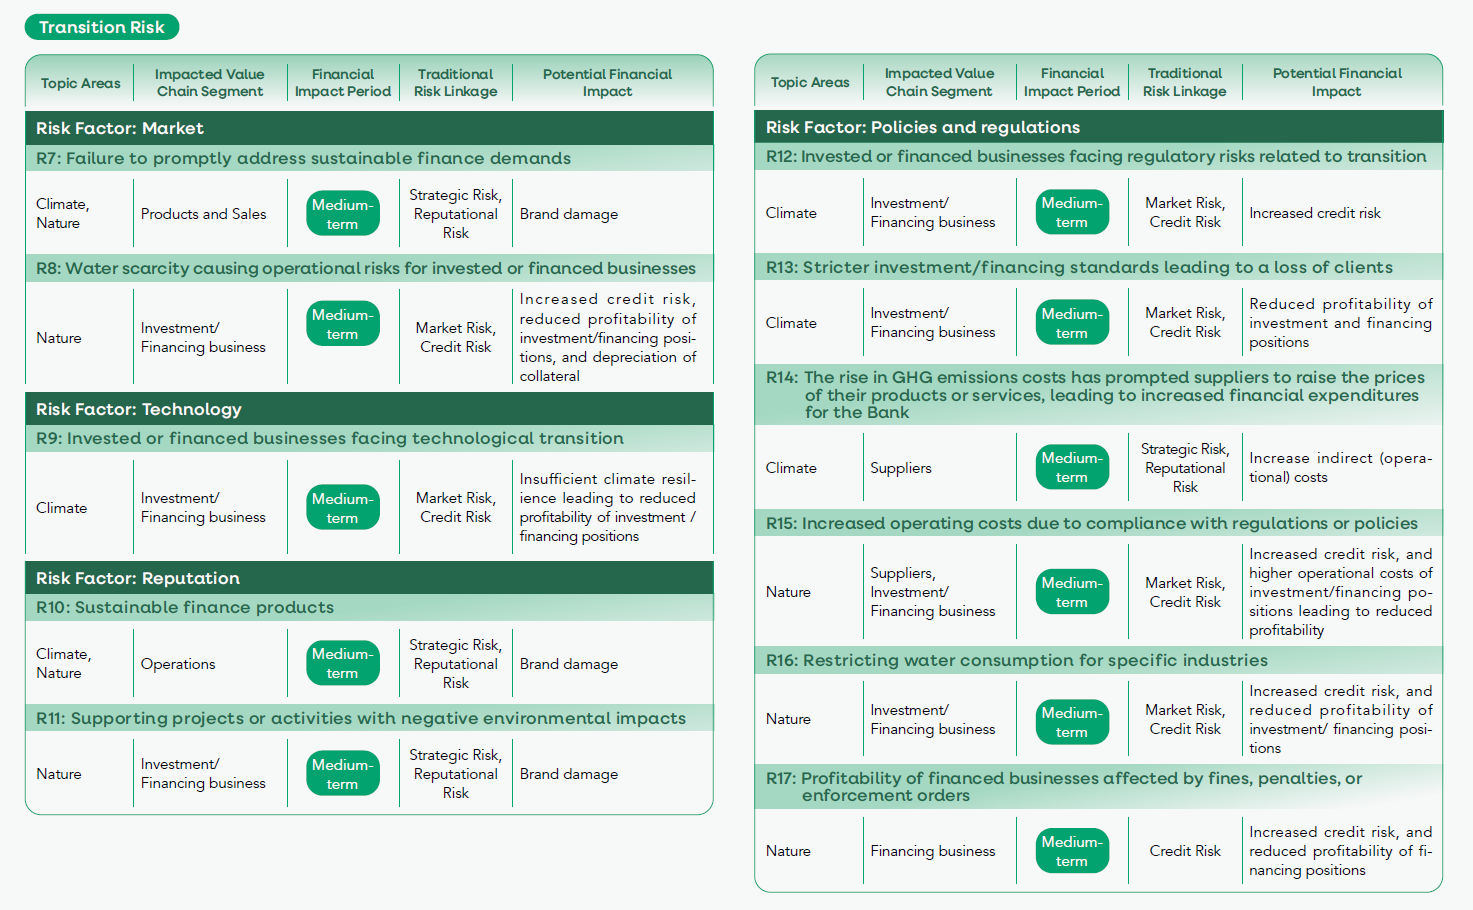
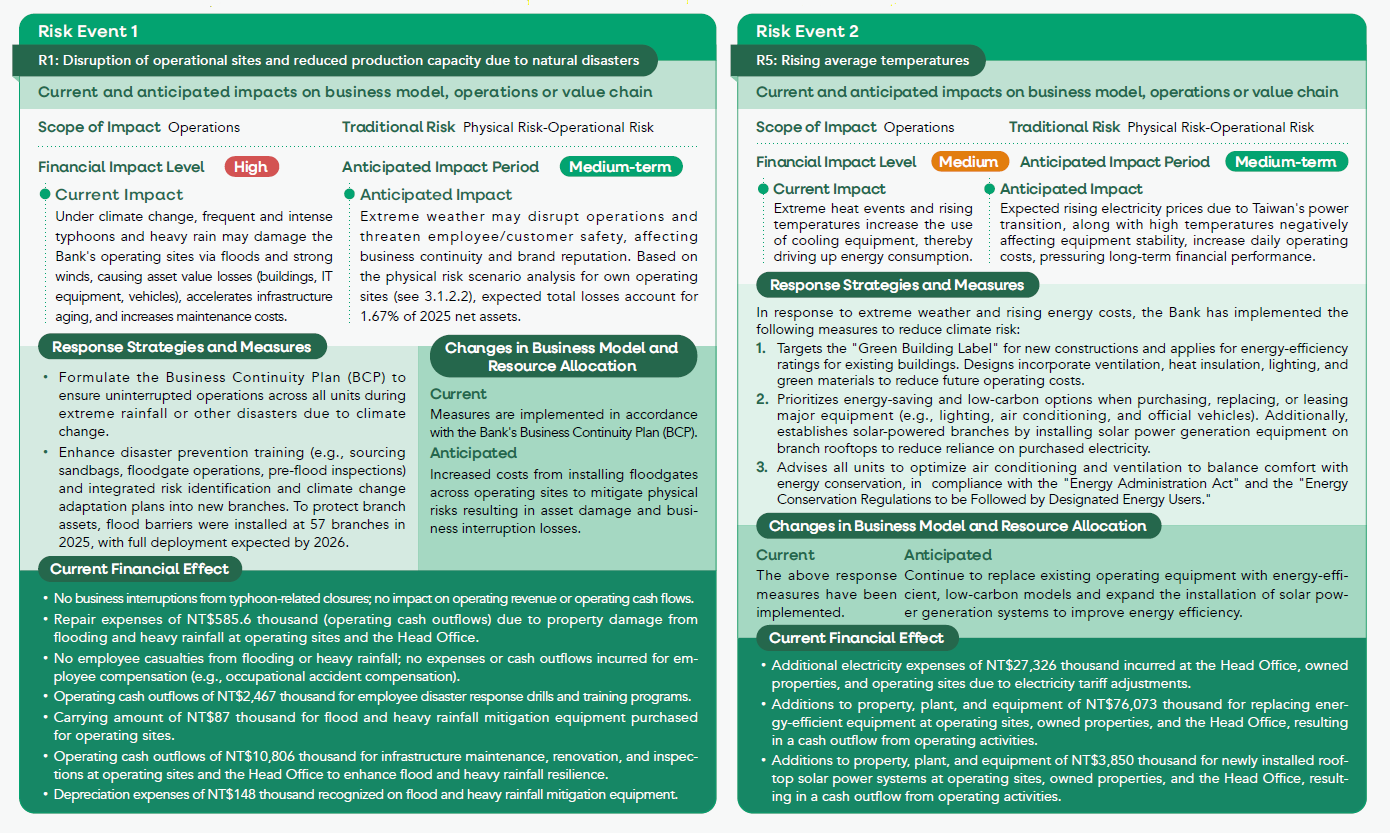
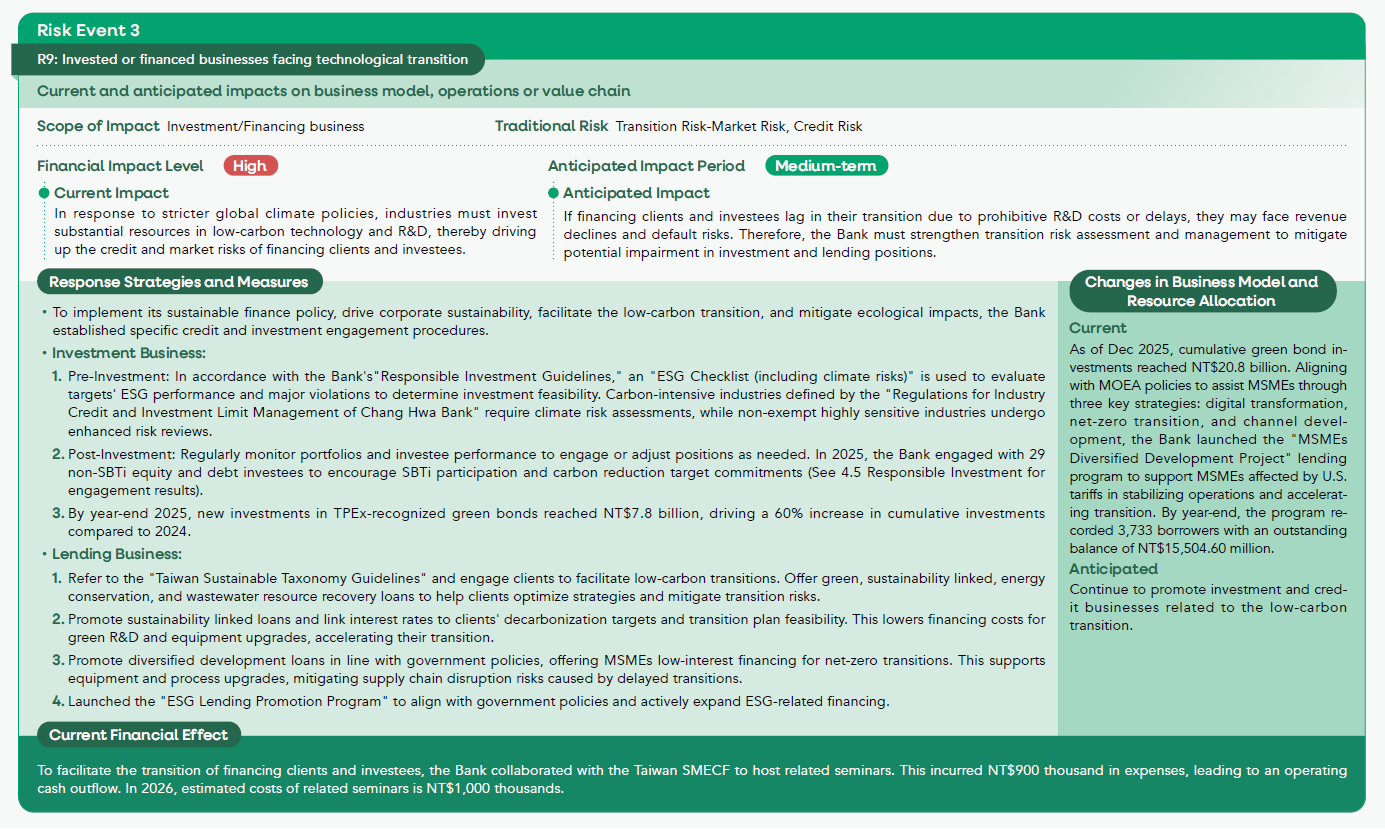
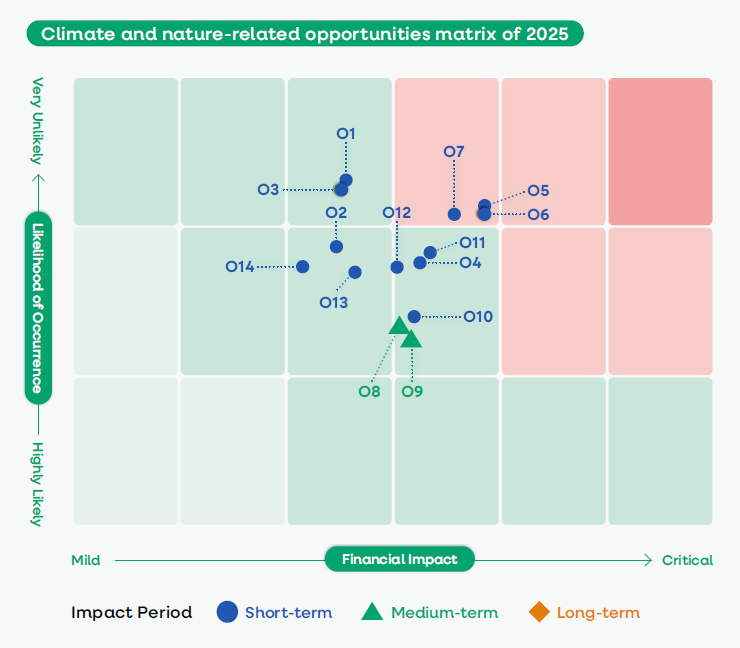
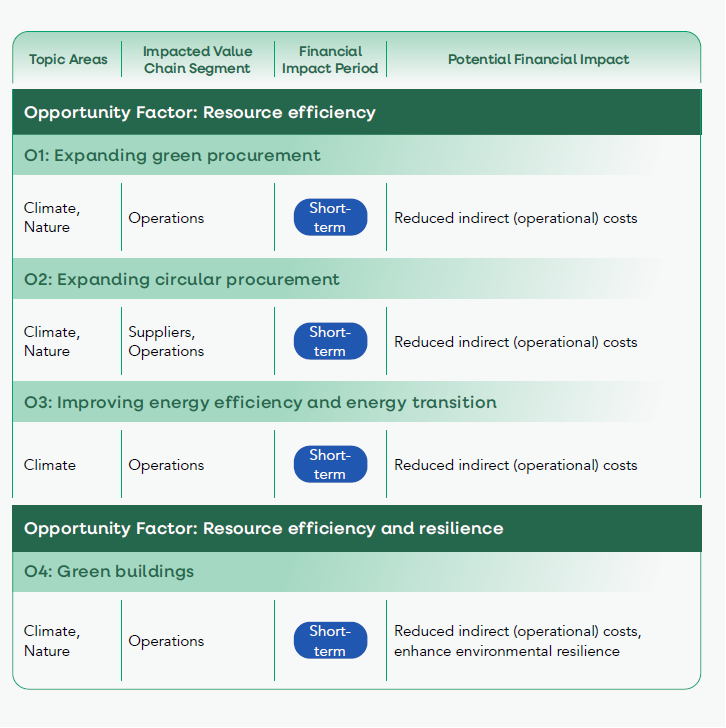
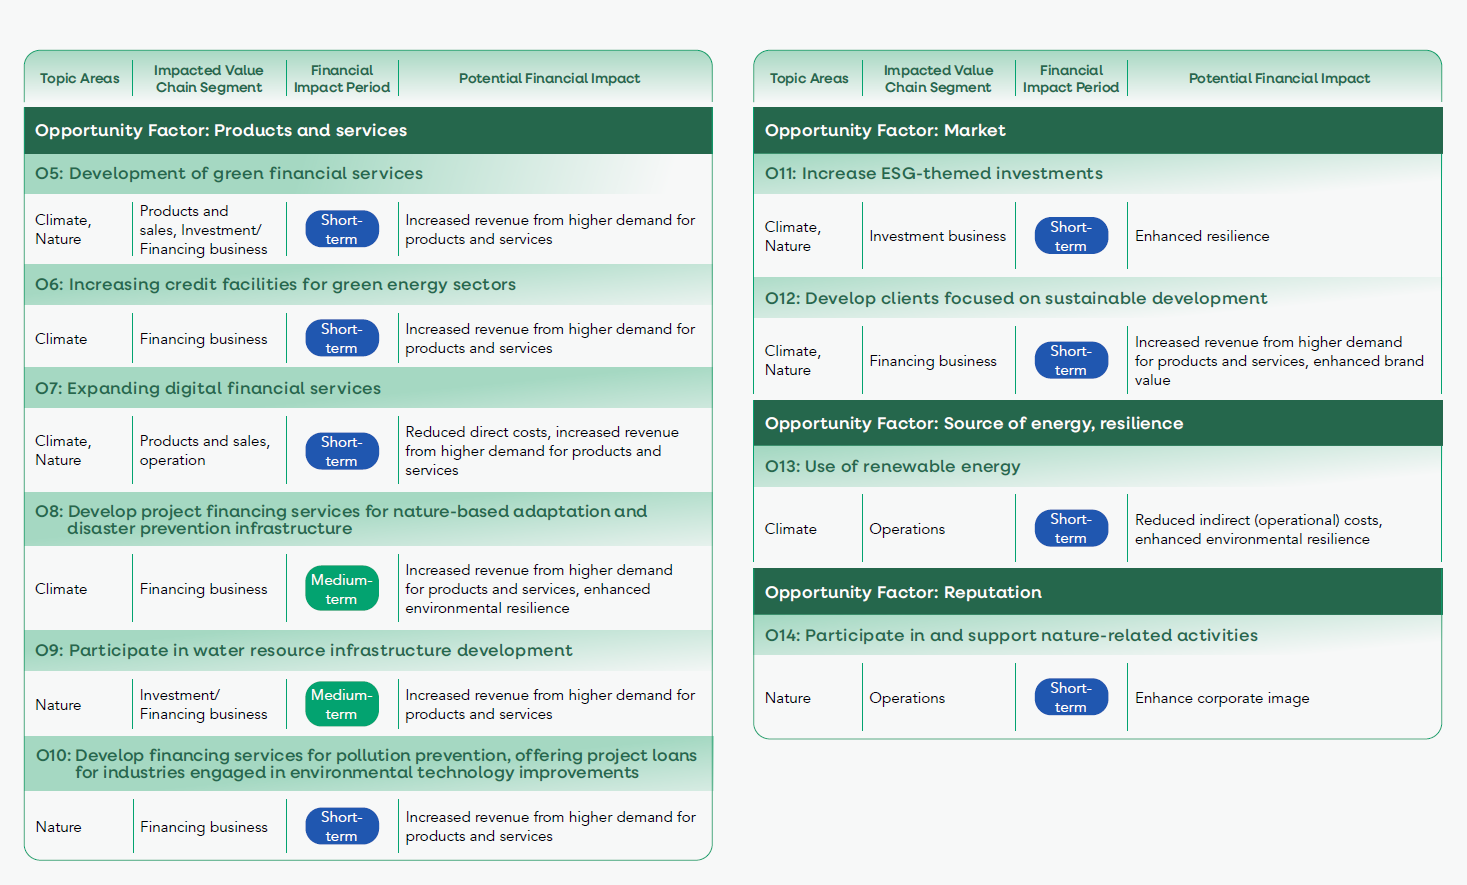
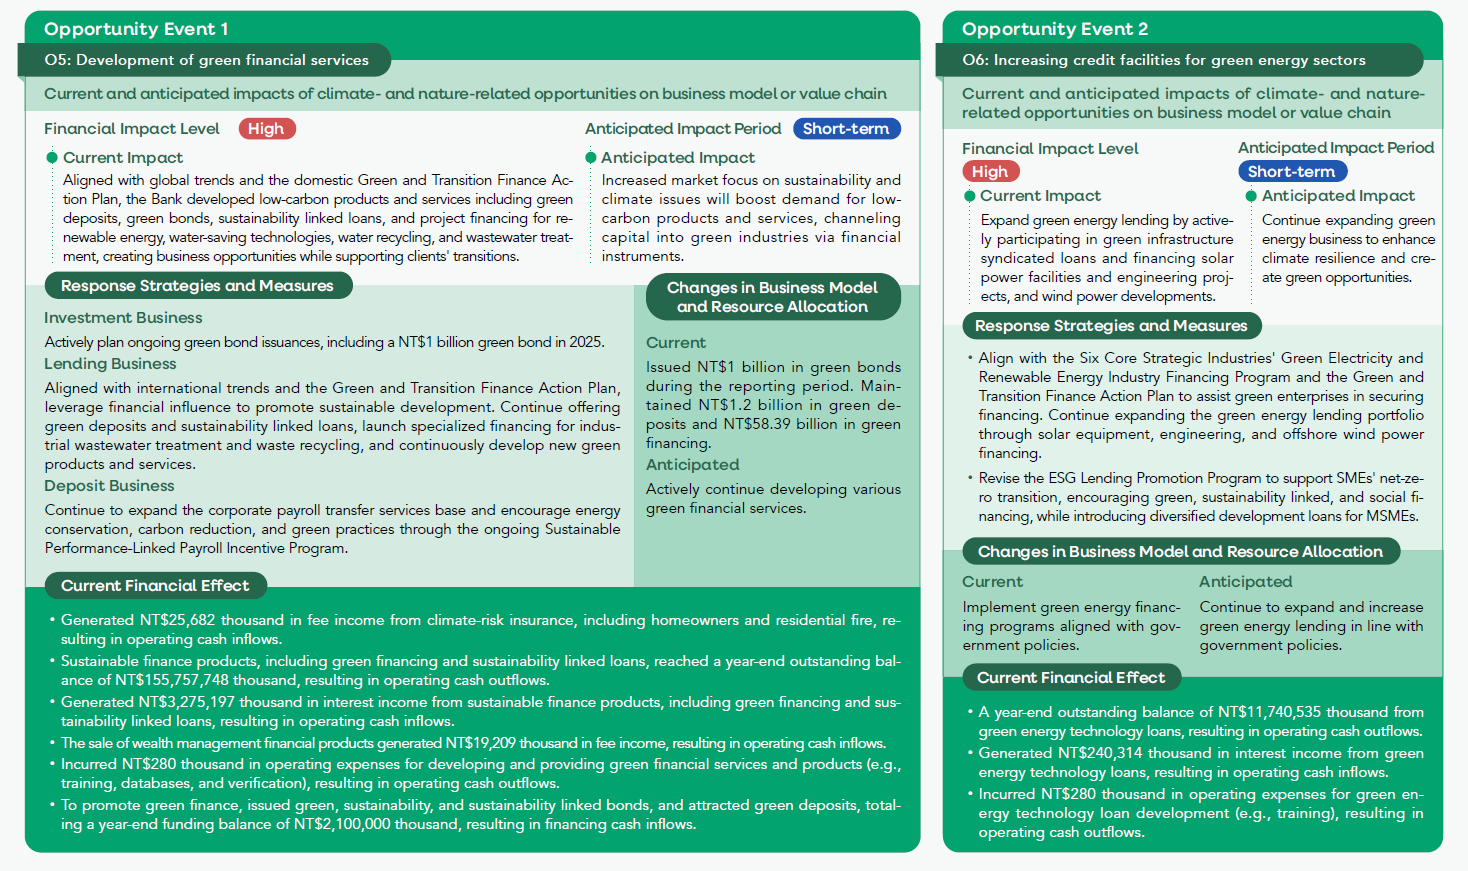
Climate-Related Scenario Analysis and Assessment of Climate Resilience
Scenario Analysis and Assessment of Strategy and Business Model
Taking into account the domestic transition status and the severity of climate risks, the Bank has defined both long-term and short-term scenarios for subsequent climate change scenario analysis. The long-term scenarios take into consideration the time scale of climate change and the business cycles of the banking industry, and are set with time horizons in the 2030s and 2050s. The short-term scenario assessment focuses on climate events expected to occur within the next year.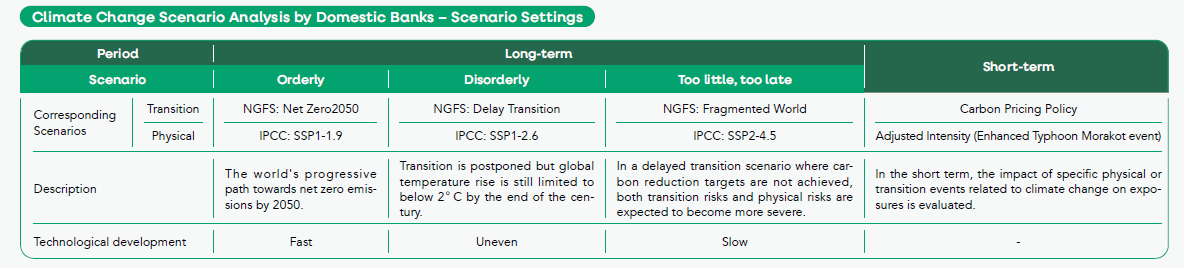
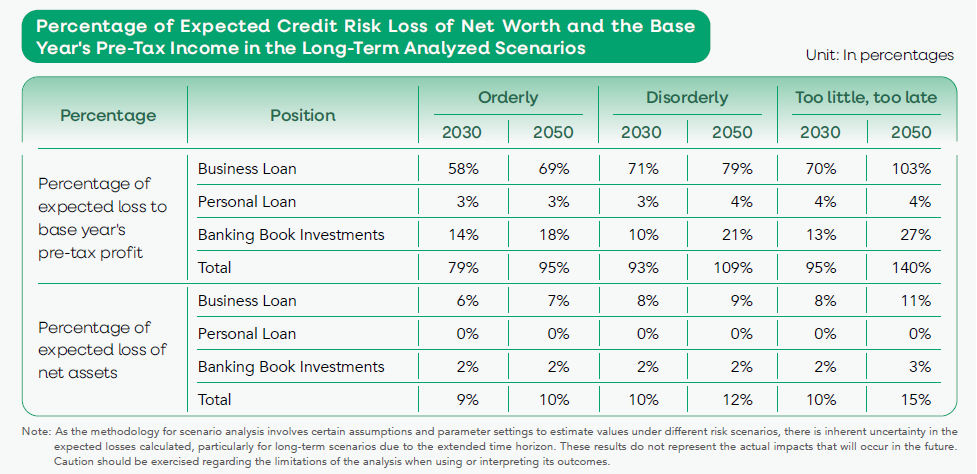
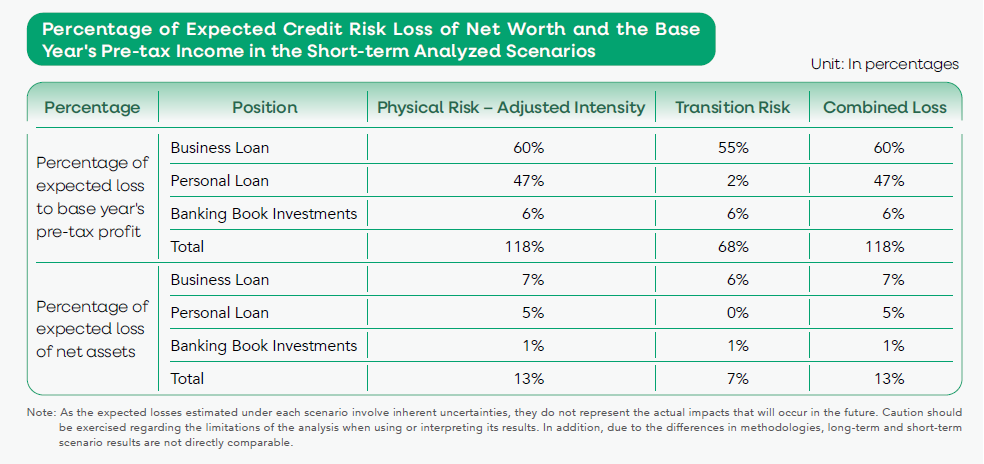
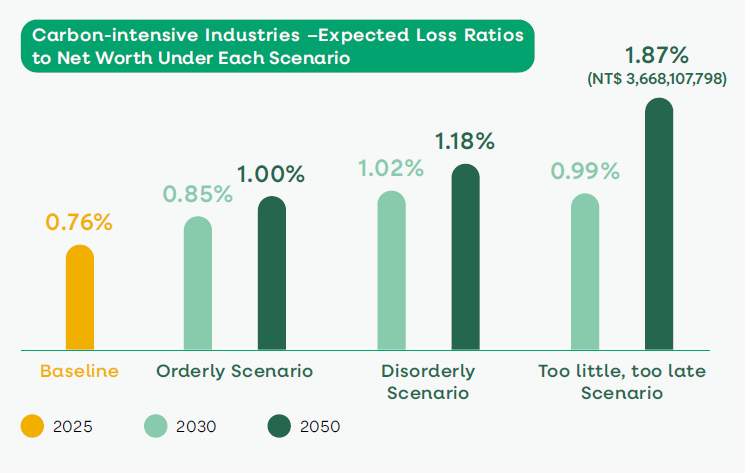
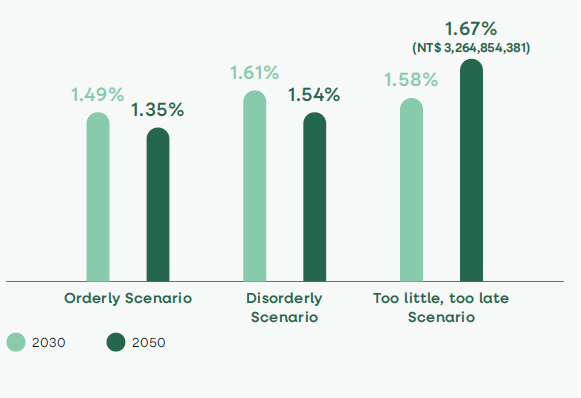
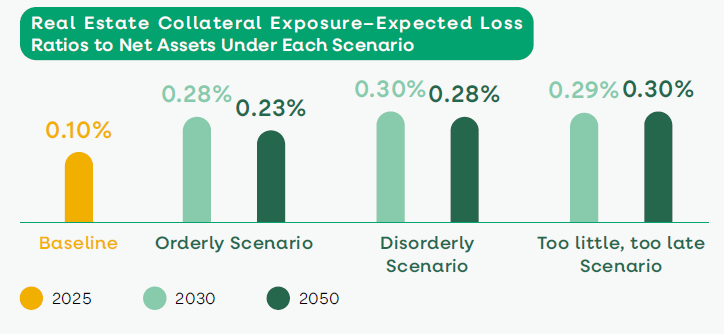
Financial Impact of Industry Transition Risks and Physical Risks Associated with High Credit Concentration
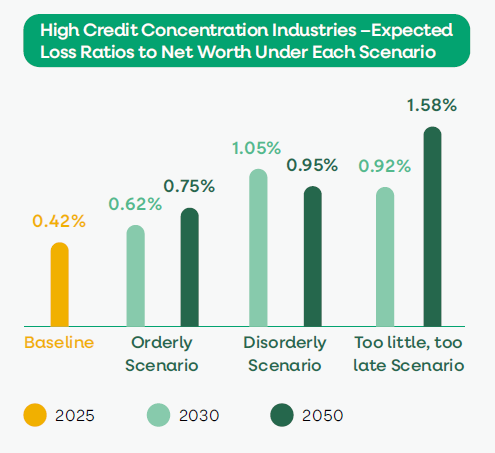
Scenario Analysis for Transition Risks
Scenario Analysis for Physical Risks
|
Scenario
|
Adjusted Intensity Scenario and Extreme Distribution Scenario in 2025
|
||
|
Risk Level of Company/ Factory Registration Address
|
Number of Suppliers
|
Transaction Amount (NT$ million)
|
Proportion of Transaction Amount (%)
|
|
High
|
0
|
0
|
0.0
|
|
Medium
|
4
|
30.82
|
4.3
|
|
Low
|
43
|
678.48
|
95.7
|
|
Total
|
47
|
709.30
|
100
|
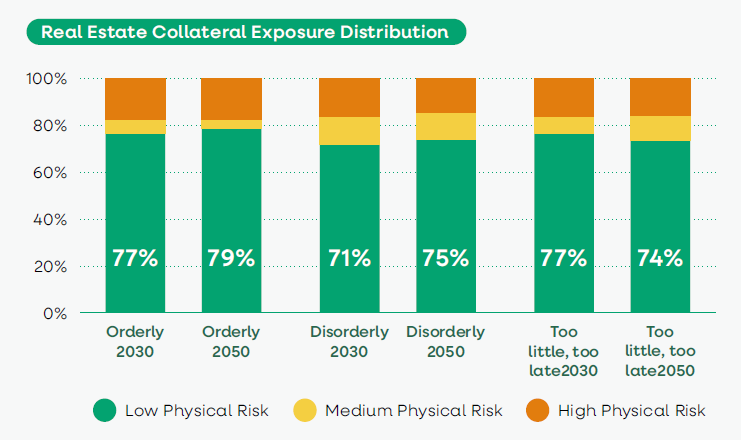
Climate Risk Stress Test – Hong Kong Branch
To achieve the 42% reduction in Scope 1 and Scope 2 (Category 1 and Category 2) emissions by 2030 from the 2020 baseline, the Bank has established 3 key carbon reduction strategies: 1. Enhancing energy efficiency in air conditioning and lighting systems. 2. Transitioning from fuel-powered vehicles to hybrid or fully electric vehicles. 3. Increasing the use of renewable energy to bridge the remaining carbon reduction gap. The Bank has also developed climate adaptation plans tailored to the climate risk levels of its operating locations, gradually moving toward the net-zero goal. The Bank recognizes that financial institutions play a critical role in driving sustainable transitions and supporting a low-carbon economy by channeling capital and offering financial products and services to assist enterprises in their low-carbon transformation. The Bank actively plans and issues green bonds and expands green loans and deposits to capture climate-related opportunities and business prospects. It also strengthens engagement with carbon-intensive industries to guide their transition to low-carbon operations and gradually reduces non-green financing to these industries. In addition, the Bank actively reviews the carbon reduction strategies of its investment and lending portfolios and underlying assets, in alignment with the SBTi's target to limit global warming to wellbelow 2 ° C. Key assumptions, factors, and conditions considered in the assessment of climate resilience include:
|
Climate- and Naturerelated Actions
|
Current Mitigation and Adaptation Efforts
|
Planned Mitigation and Adaptation Efforts
|
Direct Actions
|
Indirect Actions
|
|
Reduce GHG Emissions: Annual Scope 1 and 2 (Category 1 and 2) emissions across all domestic and overseas locations.
|
Set KPIs to reduce water, electricity, and fuel consumption, and increase renewable energy use.
|
To assist suppliers in carbon management: 1. Add a GHG inventory link on the official website. 2. Hold supplier awareness seminars. |
V
|
|
|
Implement climate adaptation plans to reduce the impact of climate change and extreme rainfall.
|
Adaptation measures at high-climate- risk operating sites include installing floodgates, equipping security systems with flood warning devices, or procuring natural disaster insurance, gradually increasing the implementation coverage of these measures to 100%.
|
In response to increasingly frequent extreme weather events, plan to implement the following climate adaptation and disaster prevention actions: 1. Disaster prevention awareness campaigns. 2. Installation of floodgates 3. Expand property insurance coverage to include typhoon, flood, and earthquake insurance. |
V
|
|
|
Increase green investments in climate, environmental, energy-saving, and carbon reduction projects.
|
Actively invested in green bonds and green industries, and established relevant KPIs.
|
Continuously increase the Bank's green investment ratio.
|
V
|
|
|
Completed engagements with high-climate-risk and carbon-intensive counterparties to guide their sustainable development and low-carbon transition.
|
Implemented "Chang Hwa Bank Credit Engagement Implementation Procedures" to actively conduct counterparty engagements.
|
Continuously engage with counterparties to align with the government's 2050 Net-Zero policy, directing capital toward sustainable activities to drive transition and reduce ecological impacts.
|
V
|
|
|
Expand low-carbon financial products and services
|
1. Boosted mobile insurance products and launched promotional campaigns to increase usage. 2. Set a KPI for the ratio of new green financial products to total newly launched wealth management products. |
1. Continuously boost mobile insurance usage. 2. Established an ESG fund setion for investors and integrate green financial products into fund promotional campaigns for frontline sales. |
V
|
|
|
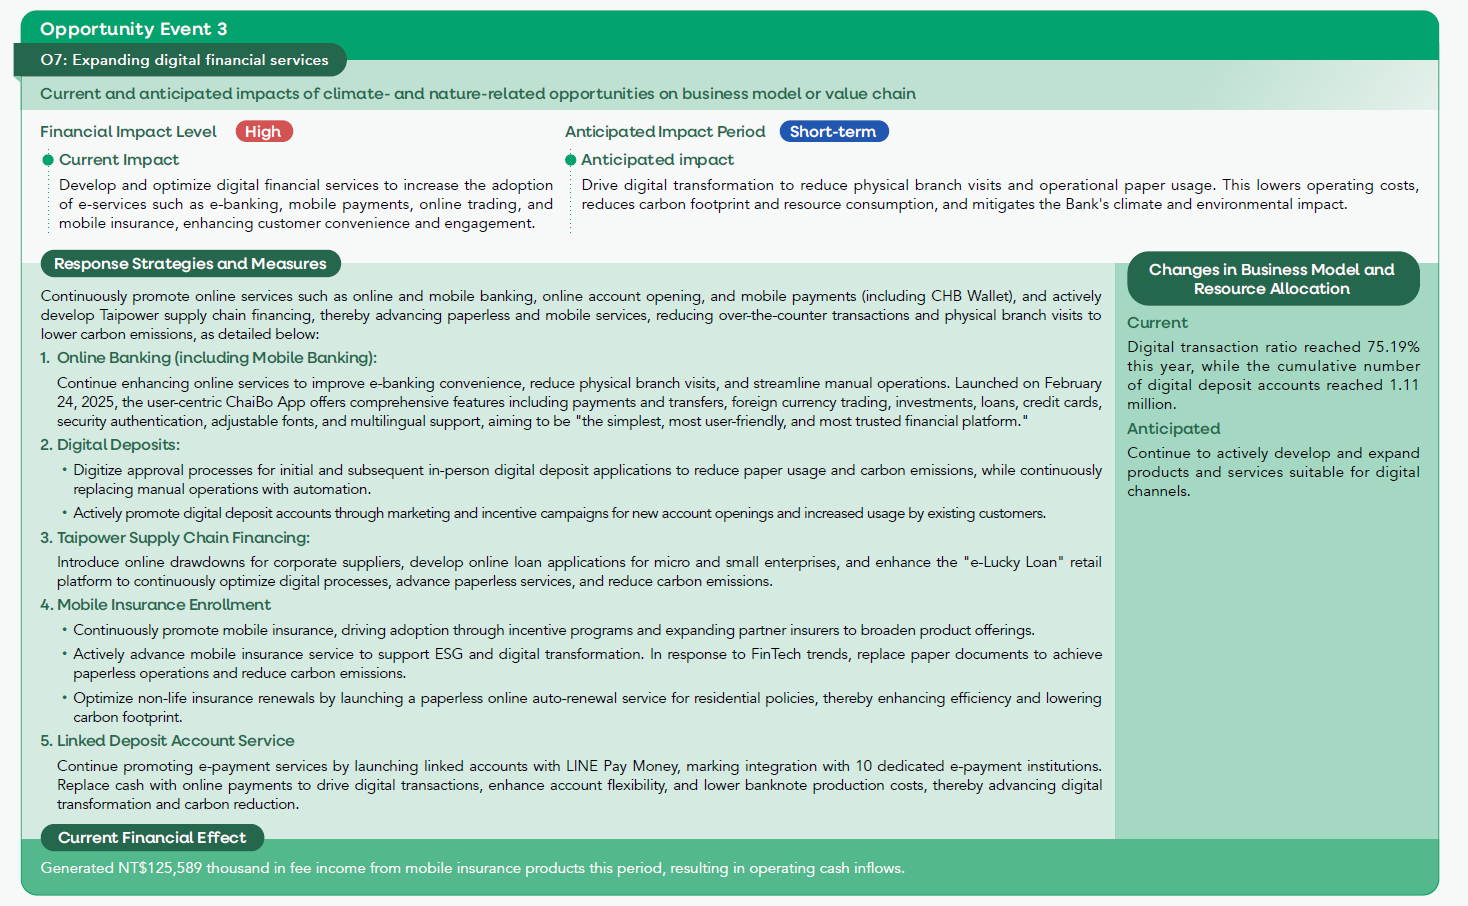
Expand digital financial services
|
1. Increase the volume of e-statements sent. 2. Increase digital deposit accounts. 3. Increase the proportion of e-transactions to total transaction volume. |
Continuously plan and increase promotional campaigns for digital financial services to implement paperless policies and achieve carbon reduction targets.
|
V
|


